Shriram Properties CMD Murali M said on Wednesday, September 23, 2026, that the company is targeting doubling its net profit and sales bookings by FY29, according to a report by ThePrint. The Bengaluru-headquartered developer, which reported a consolidated net profit of Rs 100.81 crore on sales bookings of Rs 2,354 crore in FY26, is aiming for realisable income of around Rs 3,000 crore by FY29, up from roughly Rs 1,400 crore in FY26. Alongside this growth target, the company is exploring a mall-led rental income stream in West Bengal, a move that would add a recurring commercial revenue line to a business that has historically been almost entirely residential.
1. What the FY29 Target Actually Says
Doubling both net profit and sales bookings within roughly three years is an ambitious target for any listed developer, and the company's own explanation for how it plans to get there is fairly specific: a substantial increase in revenue recognition as projects currently under construction move towards completion. Under Indian accounting norms, developers recognise most residential revenue only as units are handed over, not when they're initially sold. That means a large pipeline of projects launched over the past two to three years is now approaching the stage where their revenue starts showing up meaningfully on the income statement, a dynamic that can produce a sharp acceleration in reported profit without necessarily requiring an equivalent jump in new sales activity.
2. The Bengal Mall Plan Is the More Unusual Detail
Shriram Properties has built its business almost entirely around residential apartments and plotted developments across Bengaluru, Chennai, Kolkata and a handful of other cities. Exploring a mall-led rental income stream in Bengal marks a notable diversification, commercial rental income tends to be stickier and less cyclical than residential sales revenue, which can smooth out a developer's earnings across market cycles. It's worth being clear that this is described as an exploratory step rather than a confirmed project with a site, timeline or investment figure attached, so it shouldn't be read as an imminent launch.
- The target leans on execution, not fresh capital raising. The stated path to FY29 growth is about completing and recognising revenue on the existing pipeline, which is a more conservative growth story than one built on aggressive new land buying.
- Commercial diversification is still early-stage. The Bengal mall exploration signals strategic intent to add recurring income, but buyers evaluating a Shriram residential project today shouldn't factor this into their decision, it doesn't change anything about ongoing construction or delivery timelines.
- A credible growth target is a reasonable proxy for balance sheet health. A developer confident enough to publicly commit to doubling profit in three years is typically one with visibility into its construction pipeline and collections, which matters for anyone weighing possession-date reliability on a live project.
3. What This Means If You're Evaluating a Shriram Project
Company-level financial targets are a useful backdrop, but they don't substitute for project-specific due diligence. Whichever Shriram development you're considering, verify its RERA registration, construction stage and payment schedule independently rather than relying on the parent company's broader growth narrative. That said, a developer targeting a near-doubling of profitability by FY29, on the back of projects already under construction rather than speculative new launches, is a reasonably encouraging signal for anyone holding or considering a unit in Shriram's existing pipeline.
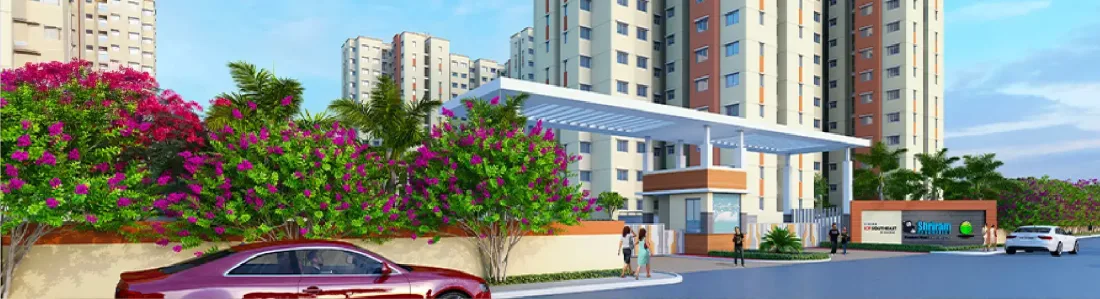
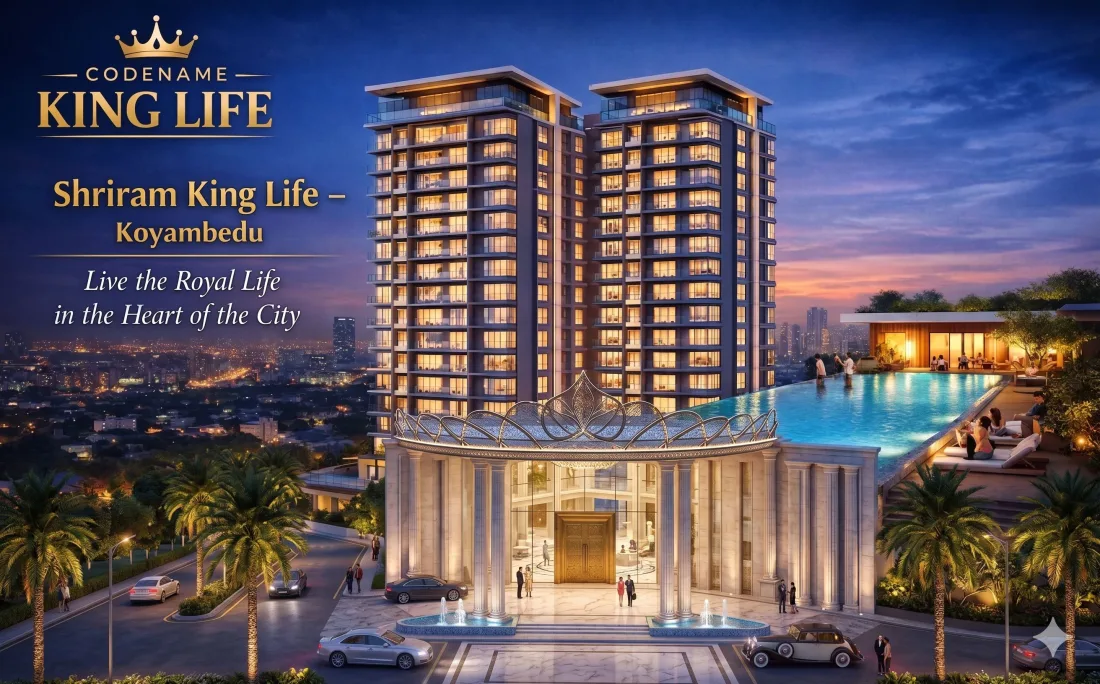
Luxura Habitat currently markets multiple Shriram Properties developments across Bengaluru and Chennai. Shriram 107 SouthEast in Attibele offers 2 and 3 BHK apartments from Rs 65 Lakh onwards, roughly 15 minutes from Electronic City, with Phase 3 currently under construction and RERA registered. In Chennai, Shriram Kinglife offers 135 low-density 3 and 4 BHK residences on a 1.96-acre tower in Koyambedu, priced from Rs 2.36 Cr onwards and RERA registered.
The Bottom Line
Shriram Properties' FY29 target is a company-level growth story built primarily on converting its existing construction pipeline into recognised revenue, with an early-stage commercial diversification plan in Bengal on the side. For buyers of its Bengaluru and Chennai residential projects, it's a reasonable, if indirect, signal of financial discipline, though it changes nothing about the project-specific checks that still matter most. Talk to our team if you'd like a closer look at current pricing and availability across Shriram's live projects.