Home loan rates across India's major banks have stayed largely stable through September 2026, but the spread between lenders remains wide enough to matter. As of mid-September 2026, SBI's home loan rates range from about 7.25% to 8.55% across its loan-amount slabs, HDFC Bank starts at around 7.75%, and ICICI Bank starts slightly lower at roughly 7.55%, according to rate comparisons published by Zeebiz and CreditMantri. Axis Bank starts at about 8%, while Bank of Maharashtra and Central Bank of India currently offer some of the lowest starting rates in the market, at around 7%, with Bank of India close behind at about 7.10%.
1. Why Rates Have Stayed Stable
This stability traces back to the RBI's policy stance. The repo rate has held at 5.25% through 2026 after the Monetary Policy Committee cut it by 25 basis points in December 2025, citing strong FY26 growth expectations of around 7.3% and low inflation of about 2%. Since the large majority of retail home loans are now linked to external benchmarks, primarily the repo rate, banks haven't had reason to move their lending rates meaningfully in either direction this quarter. For borrowers, that means the rate you lock in today is unlikely to shift dramatically over the next few months, barring a change in the RBI's stance at a future Monetary Policy Committee meeting.
2. What the Spread Between Banks Actually Means
A gap of roughly 0.5 to 0.8 percentage points between the lowest and highest starting rates among major lenders sounds small in isolation, but compounds meaningfully over a typical 20-year home loan tenure. On a Rs 75 lakh loan, for instance, the difference between an 7.25% and a 7.75% rate works out to several lakhs of rupees in additional interest paid over the loan's lifetime, even though the monthly EMI difference might look modest at first glance.
- Public sector banks currently lead on headline rates. Bank of Maharashtra, Central Bank of India and SBI's lower slabs are among the most competitive starting points in the market this month, though actual sanctioned rates depend heavily on credit score, income documentation and loan-to-value ratio.
- Private banks compete on service and turnaround. HDFC and ICICI's rates sit a touch higher on paper but are often bundled with faster processing, digital disbursal and better developer tie-ups for approved projects, which can matter for a time-sensitive booking.
- Your actual rate depends on your profile, not just the bank's headline number. The published "starting from" rate typically applies to the strongest borrower profiles; most applicants should expect an offer somewhat above the advertised floor.
3. What This Means for Bangalore and Chennai Buyers
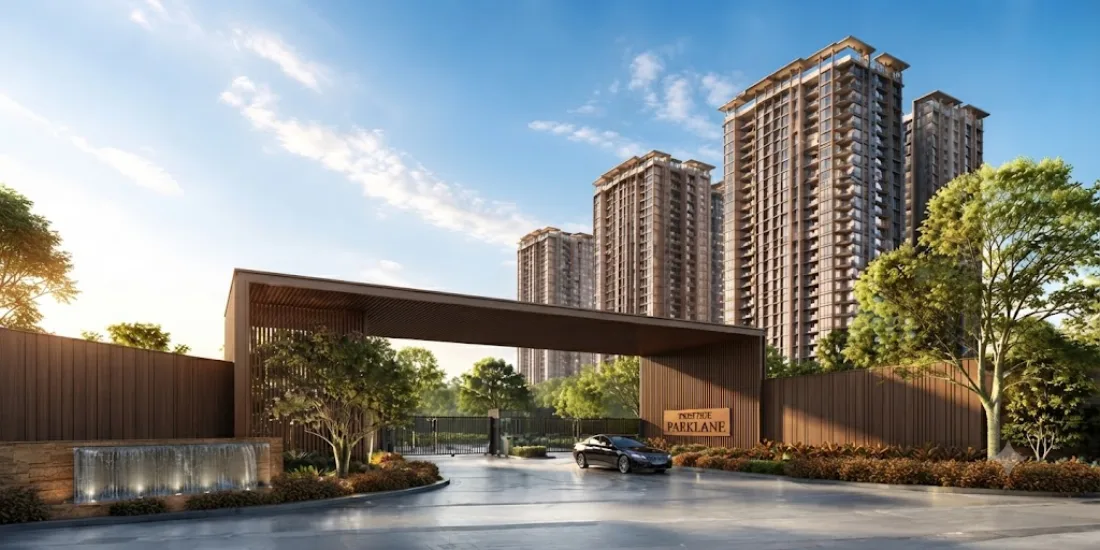
For buyers currently evaluating a purchase, whether it's a new launch like Prestige Parklane in Devanahalli or a project in Chennai's western corridors, a stable rate environment removes one variable from the decision. It's still worth shopping the loan separately from the property: approach at least three or four lenders, including your existing salary or savings account bank (which often offers a small relationship discount), and factor in processing fees, prepayment terms and whether the bank has an existing tie-up with your chosen developer, which can sometimes speed up disbursal against construction-linked payment plans.
The Bottom Line
Home loan rates in September 2026 remain broadly stable across lenders, tracking a steady RBI repo rate, but a meaningful spread persists between the most and least competitive offers. For a purchase of the size most buyers in Bangalore or Chennai are making, taking the time to compare a handful of lenders before signing is worth several lakhs of rupees over the life of the loan. Talk to our team for a referral to lenders with active tie-ups on the projects we work with.